
Retirement planning isn't a solo sport. The right tool keeps you and your client on the same screen, working through the decision while the question is still on the table.
The Retirement Decision Window Is Where Plans Get Real
For households already retired or close enough that January 1 balances, spending, Social Security, Medicare, and tax decisions are concrete, the planning question changes. You're no longer projecting decades of accumulation. You're modeling near-term funding, Roth and RMD policy, QCDs, IRMAA, spending flexibility, and downside resilience. That's the retirement decision window. It's also where most general-purpose planning platforms start to feel like overkill. Advisors need tools that keep the reasoning visible, the assumptions explainable, and the client in the room. The five platforms below are built for that moment, each with a different center of gravity.
How We Evaluated These Retirement Decision Tools
We looked at five factors across every platform. First, service scope: does it handle the retirement decision window specifically, or is it a broader accumulation planner? Second, shared decision design: can you and your client work from the same screen, with visible input provenance and explainable assumptions? Third, modeling depth: Monte Carlo paths, tax-aware assumptions, recurring-income modeling, and matched-path analysis. Fourth, pricing clarity: is the cost structure visible enough for a small or mid-sized firm to evaluate? Fifth, local fit: does it support US-specific tax and Medicare realities like RMDs, QCDs, and IRMAA? Each platform stood out in different ways. NestWise Professional leans into the shared working session. Income Lab emphasizes retirement distribution planning and market share. RightCapital brings broad planning and tax tools. MaxiFi centers on economics-based lifetime planning. WealthTrace offers DIY-friendly projections with account linking.
Here's a quick look at how these five platforms compare on the factors that matter most for advisor-led retirement decisions.
| Provider | Best For |
|---|---|
| Income Lab | Advisors who want a distribution-first planning workflow with AI support |
| NestWise Professional | Retirement Decisions, Made Together | Advisors who want a shared, explainable decision session with clients |
| RightCapital | Advisors who want broad planning features with strong tax and Roth tools |
| MaxiFi | Advisors who want economics-based lifetime planning and Roth optimization |
| WealthTrace | Advisors who want account-linked projections with tax and withdrawal analysis |
The 5 Tools in Focus
#1 Income Lab
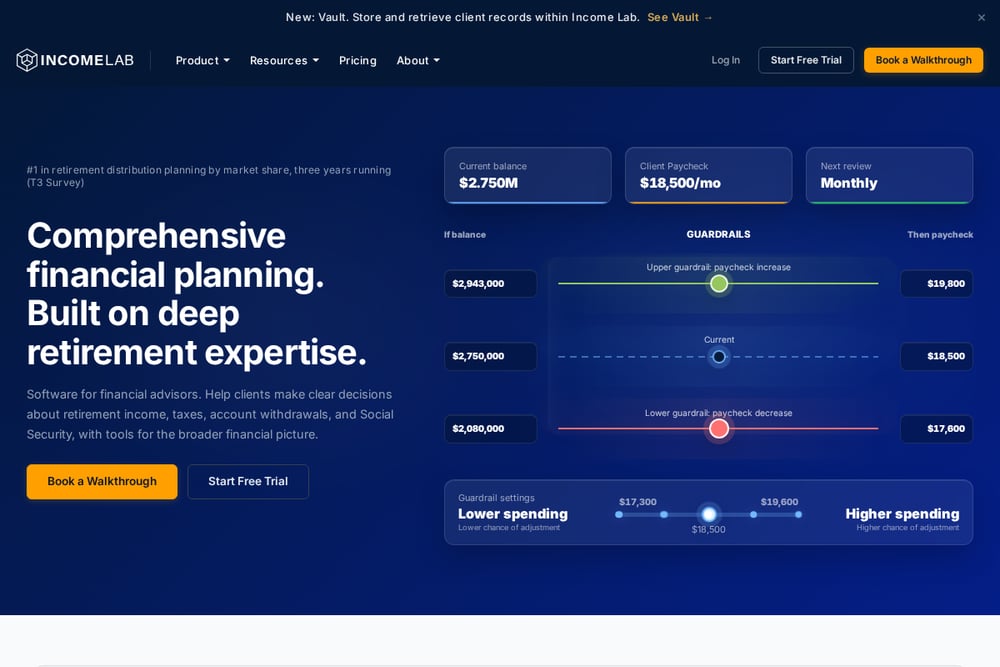 A screenshot of the Income Lab website.
Income Lab positions itself around retirement distribution planning, answering the question 'how much can I spend?' in dollars. Its planning tools include Retirement Planning, Tax Lab, Withdrawal Optimizer, Life Hub, Social Security Optimizer, and Vault for storing and retrieving client records. The platform also offers AI tools like Penny, an AI paraplanner, plus AI Plan Builder, AI Interviewer, AI Assistant, and AI Scribe. According to its 2026 guide, Income Lab holds the top spot in retirement distribution planning by market share in T3 surveys from 2024 to 2026, with nearly twice the market share of the next platform. For advisors who want a distribution-first workflow with a growing AI layer, it's a strong fit.
#2 NestWise Professional | Retirement Decisions, Made Together
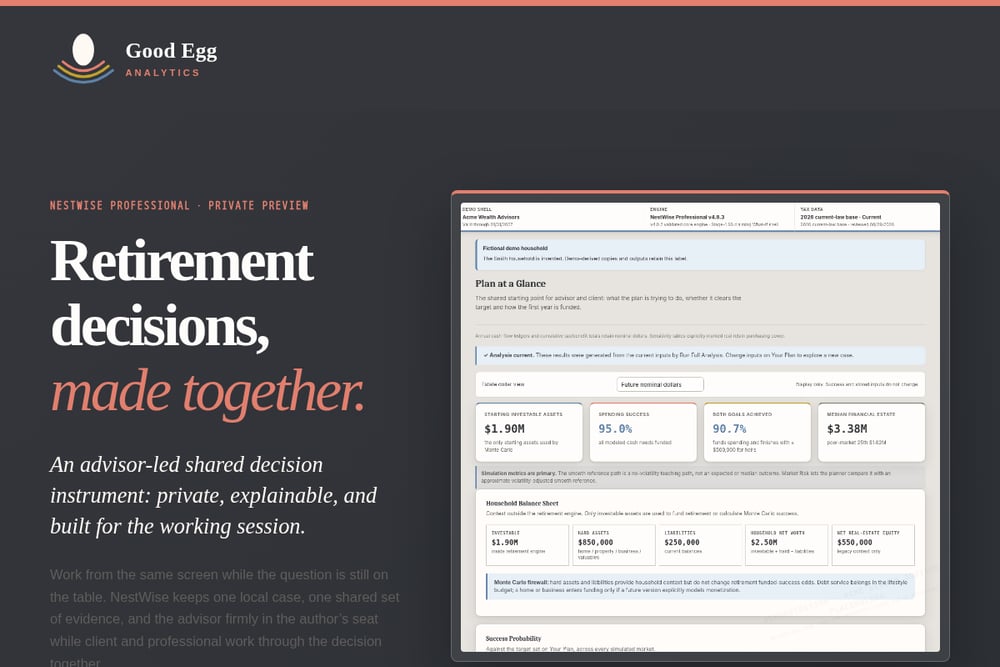 A screenshot of the NestWise Professional | Retirement Decisions, Made Together website.
NestWise Professional is an advisor-led shared decision instrument built for the working session. It keeps one local case and one shared set of evidence so you and your client can work from the same screen while the question is still on the table. The platform runs 10,000-path Monte Carlo simulations with matched paths and a bounded decision scan, and it keeps lifestyle funding, legacy context, input provenance, and the annual decision workflow visible enough to inspect together. It's designed for households already retired or close enough that opening balances, spending, Social Security, Medicare, and tax decisions are concrete. Source-aware tax assumptions and recurring-income modeling round out the near-term retirement focus. The advisor stays firmly in the author's seat throughout.
#3 RightCapital
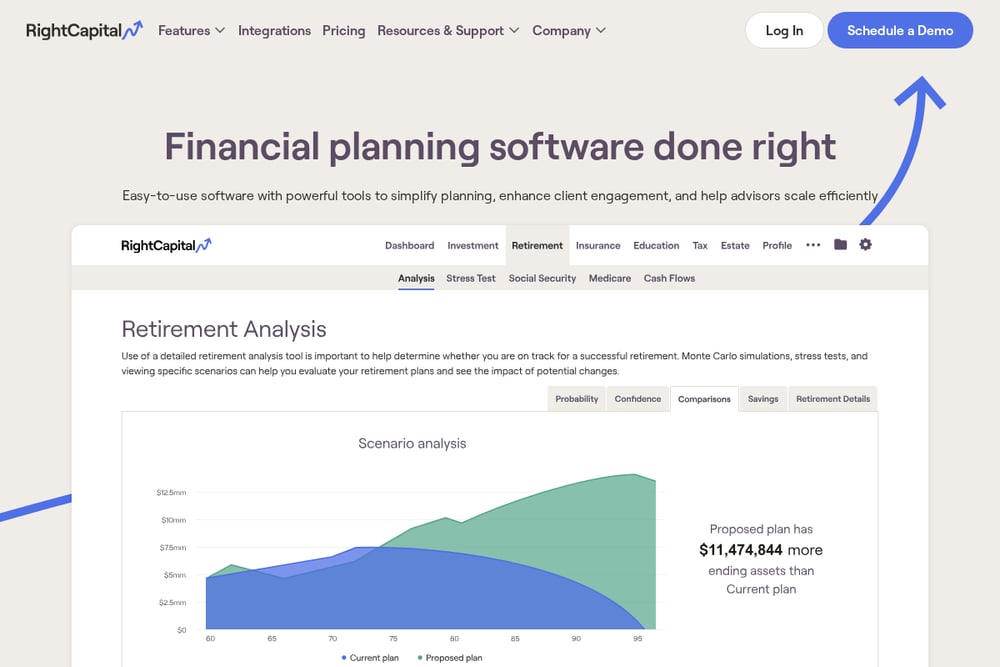 A screenshot of the RightCapital website.
RightCapital offers financial planning software with a broad feature set, including interactive retirement planning, Smart Tax Planning, Roth conversions, tax-efficient withdrawals, and asset location analysis. Its Tax Analyzer helps identify tax savings opportunities, while Smart Import uses AI to streamline data entry. The platform also includes RightFlows workflows for growing firms, RightIntel built-in firm intelligence, and Iris, an AI planning agent. According to Income Lab's 2026 guide, RightCapital scored 8.40/10 in the same T3 survey and earned an honorable mention based on user interface and ease of use. For advisors who want a wide planning surface with strong tax tools, it's worth a look.
#4 MaxiFi
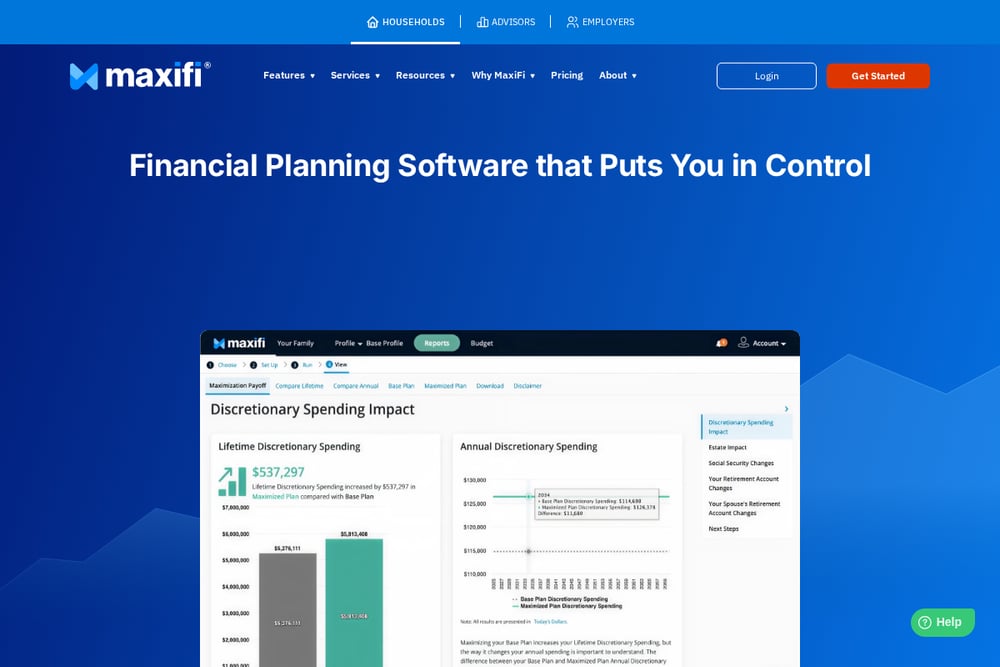 A screenshot of the MaxiFi website.
MaxiFi takes an economics-based approach to lifetime planning, with a focus on living standard optimization. Its features include a Roth Conversion Optimizer, Living Standard Monte Carlo, and life insurance contingency planning. The platform serves households, advisors, and employers, and offers service tiers like Flight Check, Co-Pilot, and Concierge for different levels of support. MaxiFi's methodology comes from a world-renowned economist, and the platform emphasizes clarity and confidence in lifetime financial decisions. For advisors who want an economics-driven lens on retirement and tax optimization, it's a distinctive option.
#5 WealthTrace
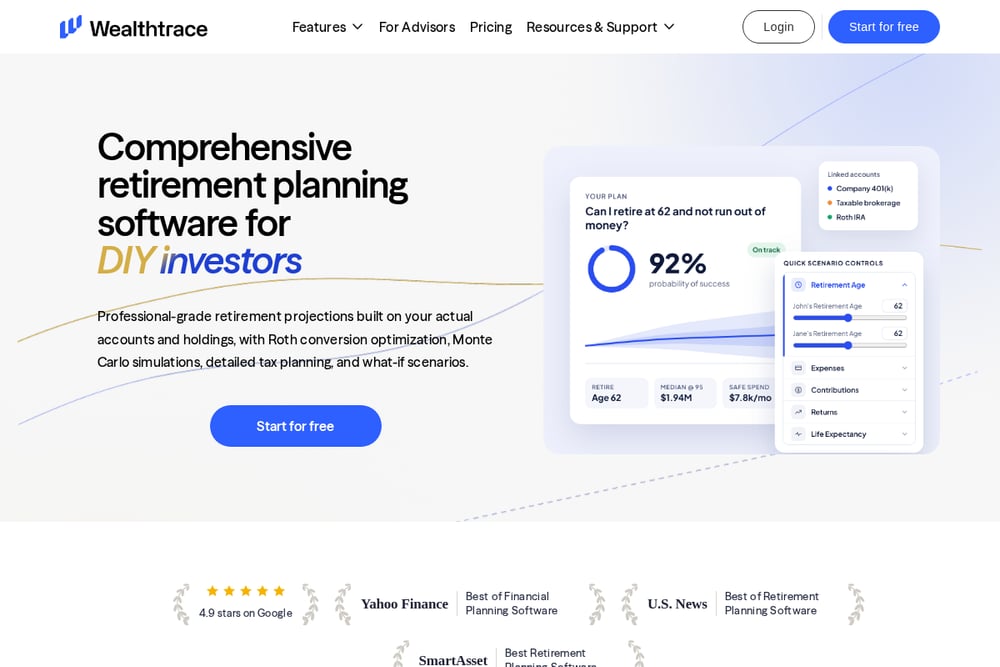 A screenshot of the WealthTrace website.
WealthTrace provides comprehensive retirement planning software for DIY investors and advisors, built on actual accounts and holdings. It offers Monte Carlo simulations, Roth conversion optimization, detailed tax planning, RMD projections, and what-if scenarios. You can link investment accounts, analyze holdings-level performance, and see how actual investments impact retirement projections. The platform has earned recognition from Yahoo Finance, U.S. News, and SmartAsset, and holds a 4.9-star rating on Google. For advisors who want account-linked projections with tax and withdrawal analysis, it's a practical choice.
How to Choose the Right Fit for Your Practice
Start with the decision you're actually trying to support. If your clients are in the retirement decision window, prioritize tools that keep the reasoning visible and the assumptions explainable. If you need broad planning across accumulation and distribution, look at platforms with wider feature sets. If tax strategy is central, weigh the depth of Roth, RMD, and withdrawal modeling. If you want to work from the same screen as your client, focus on shared decision design and input provenance. And always check pricing clarity before you commit. The right tool is the one your team will actually use in the room.
Where Automation Fits in the Retirement Decision Workflow
Automation can handle data entry, scenario setup, and repetitive modeling tasks, but it shouldn't replace the advisor's judgment. Use AI-assisted imports and plan builders to get to the first draft faster. Then use Monte Carlo and matched-path analysis to stress-test the assumptions. Keep the client in the loop with a shared screen so they can watch the reasoning and ask the next question. The goal is not to automate the decision. It's to automate the busywork so you can spend more time on the decision itself.
The Bottom Line on Advisor-Led Retirement Decisions
The retirement decision window rewards tools that keep the client and advisor on the same page. Income Lab brings distribution-first planning and a growing AI layer. NestWise Professional keeps the shared session, input provenance, and near-term tax realities front and center. RightCapital offers broad planning with strong tax tools. MaxiFi brings an economics-based lifetime lens. WealthTrace delivers account-linked projections with tax and withdrawal analysis. Pick the one that matches how you work, and let the tool do what it does best: keep the decision visible while the question is still on the table.