
Tax returns kill more FHA deals than credit scores ever will. These four lenders built their businesses around that gap.
Why VOE-Only FHA Is Having a Moment
FHA lending has quietly become the problem-solving corner of the mortgage market. Standard 203(b) loans still dominate, but a growing slice of borrowers have income that tax returns undersell: tipped workers, commission salespeople, realtors, independent contractors, and recent promotees. Verification of Employment documentation has become the workaround, letting a third party confirm income instead of chasing two years of returns. At the same time, a second lane has opened for buyers who lost a deal or do not yet qualify, using lease-to-own and entity-purchase structures. The result is a market where specialization matters more than rate sheets.
What We Looked At
Each of these four was evaluated on the same factors: how income is documented, who the program is actually built for, how clearly the eligibility rules are published, and how well the offering fits its market. The featured wholesale lender stands out for publishing exact specs (620 FICO, 45% DTI, 6% concessions) and for a partnership model that protects the broker's client relationship. Absolute Mortgage stands out for pairing the niche program with a full retail menu and a clear document checklist. Gustan Cho Associates stands out for manual-underwriting flexibility and a willingness to take on credit and DTI challenges. On Mortgage stands out for regional focus, with Florida-specific guidance and a parallel self-employed track.
Four wholesale and retail FHA options that solve the income-documentation problem, each with a different angle on who they serve.
| Provider | Best For |
|---|---|
| Absolute Mortgage | Consumers who want a full-service retail team and a broad loan menu |
| VOE-Only FHA Lender for Brokers and Credit Unions | No Tax Returns | Text Cheryl | Brokers, loan officers, and credit unions offloading hard FHA files |
| Gustan Cho Associates | Borrowers with W-2 income and no filed returns who need manual flexibility |
| On Mortgage | Florida buyers qualifying on employer-confirmed tips, bonus, or a raise |
What Separates These Four FHA Pathways
#1 Absolute Mortgage
 A screenshot of the Absolute Mortgage website.
Absolute Mortgage runs a full retail menu with a dedicated FHA no-tax-returns page, so you get a conventional storefront experience alongside the niche program. The VOE approach replaces tax returns, W-2s, and the 4506T, which speeds up files that would otherwise stall. They ask for a two-year employment history, preferably with the same employer or line of business. Business owners need a recognized brick-and-mortar operation, and non-arm's-length transactions get extra scrutiny. It is a solid fit if you want one company handling everything rather than a wholesale handoff. See the program details at https://www.absoluteml.com/fha-no-tax-returns-2/.
#2 VOE-Only FHA Lender for Brokers and Credit Unions | No Tax Returns | Text Cheryl
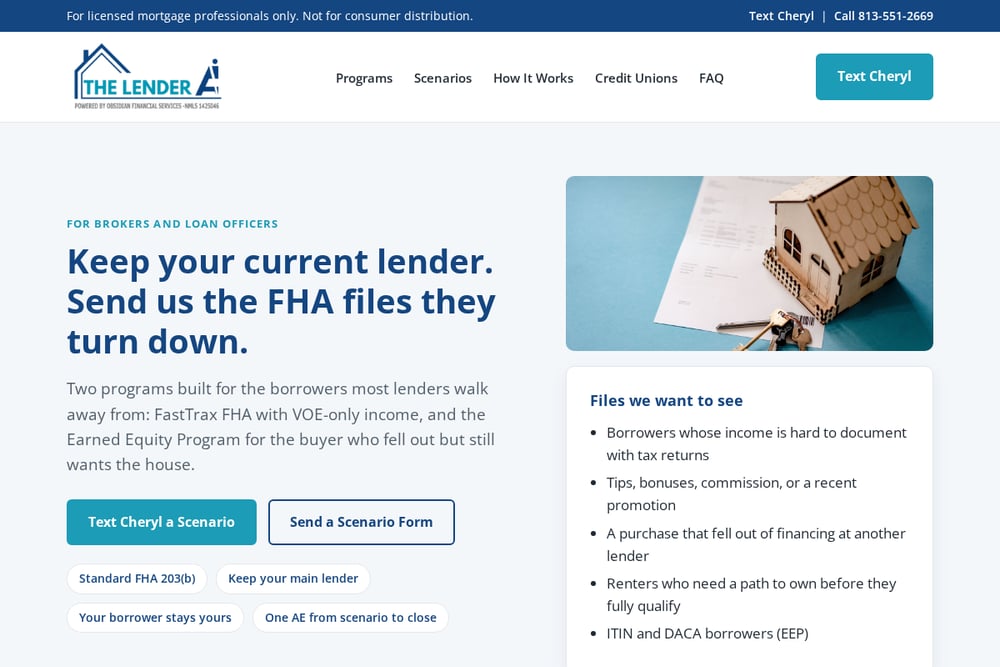 A screenshot of the VOE-Only FHA Lender for Brokers and Credit Unions | No Tax Returns | Text Cheryl website.
This is the wholesale play, and it is built for licensed mortgage professionals only, not consumer distribution. You keep your current lender and your borrower stays yours; you send over just the FHA files that do not fit your main lender's box. FastTrax FHA documents income with a third-party Verification of Employment instead of W-2s and tax returns, and it is a standard insured 203(b) run through AUS, not a non-QM product. The specs are clear: 3.5% down, 620+ FICO, 45% max DTI, 100% gift funds, up to 6% seller concessions, and cash-out to 80% LTV. A second track, the Earned Equity Program, gives buyers who fell out of financing a lease-based path to ownership. Text a scenario and one account executive takes it from scenario to close. Details at https://textcheryl.com/.
#3 Gustan Cho Associates
 A screenshot of the Gustan Cho Associates website.
Gustan Cho Associates built a reputation on the files other lenders decline, and the W-2 income-only FHA program fits that mold. You qualify on W-2 income without submitting income tax returns, which is a lifeline if your returns are thin or unfiled. The team is known for working with lower credit scores, high debt-to-income ratios, and borrowers after bankruptcy or foreclosure. That manual-underwriting mindset is the differentiator when an automated finding comes back refer. If your file needs a human to argue your case, this is the kind of shop that will try. Read the program write-up at https://gustancho.com/fha-w-2-income-only-mortgage/.
#4 On Mortgage
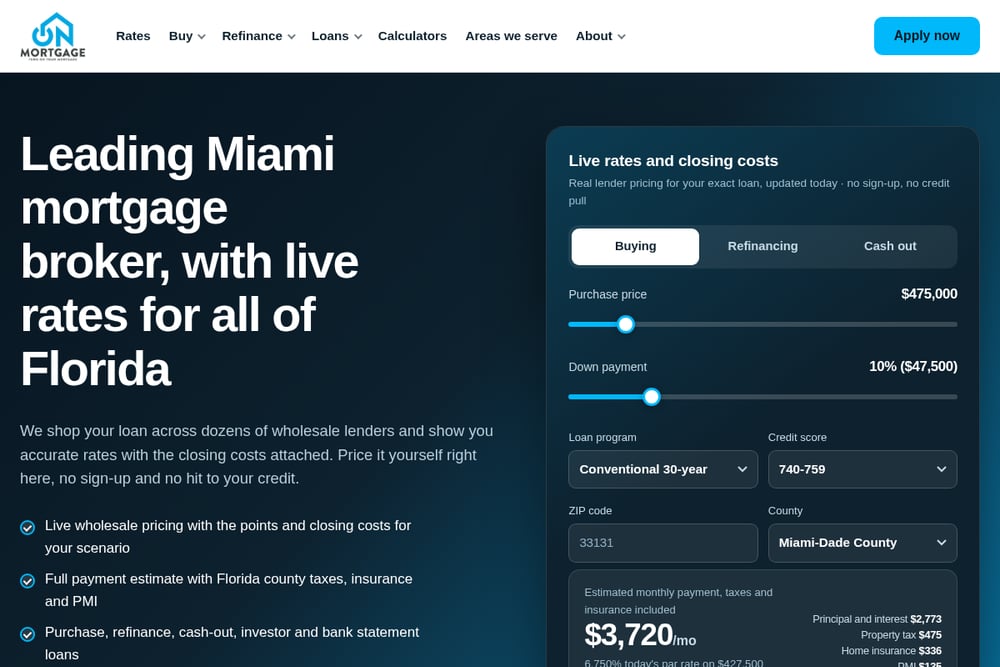 A screenshot of the On Mortgage website.
On Mortgage takes a regional approach, packaging the FHA VOE loan specifically for Florida borrowers. The pitch is simple: qualify on what your employer confirms, including tips, bonuses, and a recent raise, rather than what your returns show. They pair that with a self-employed FHA option using a CPA-prepared P&L, so business owners have a second door. The site also layers in Florida-specific guidance on down payment assistance, cash to close, and local taxes and fees. If you are buying in the Sunshine State and want a lender fluent in state programs, this is worth a call. Explore it at https://on-mortgage.com/fha-voe-loan.php.
How to Pick the Right FHA Partner
Start with your role. Licensed professionals should confirm the lender works wholesale and lets you keep the borrower relationship. Consumers should confirm whether the VOE-only option is available retail or only through a broker. Next, check the income types accepted: W-2 only, or 1099, commission, tips, and bonus too. Then verify the credit floor and DTI cap, since 620 and 45% are not universal. Ask about gift funds, seller concessions, and property types. Finally, ask what happens when the file falls outside the box, because the answer tells you how specialized the lender really is.
How the VOE-Only Workflow Actually Runs
You text a scenario, the account executive confirms eligibility, the third-party VOE replaces tax returns, and the file runs through AUS to an Approve/Eligible finding. Your borrower stays with you from scenario to close.
The Bottom Line on VOE-Only FHA
The right pick depends on who you are. If you are a broker or credit union that wants to keep the client and hand off only the hard files, the VOE-only wholesale model is the cleanest fit. If you are a consumer who wants a full-service retail team, the other three give you more hand-holding and broader loan menus. Either way, ask one question first: does this lender document income with a VOE, or will they still ask for returns?